Auction dislocation, realised intraday volatility eased broadly in August
Closing auction dislocation fell across eight of the ten indices we track, led by the FTSE China A50 (CN50, -49%, to 5.9bp), TOPIX Core30 (JP30, -28%) and Nasdaq 100 (US100, -33%). The ASX 200 (AU200) and Hangseng bucked that trend, rising 10% to 31.7bp, and 3% to 16.3bp.
Intraday volatility eased everywhere (FTSE China A50 -36%, TOPIX Core30 -26%, Nasdaq 100 -25%), except it rose in the ASX 200 (+9%).
The ASX 200's 1-second markouts also swung positive to 0.12bp, up 343% on a small base, while the Swiss Market Index's (CH20) markout fell 31% to 0.24bp.
These metrics are built from BMLL's pre-calculated daily analytics, available via the BMLL Data Feed and can be delivered directly into your existing workflows.
Contact us to discuss how this can support your market microstructure research, TCA and liquidity provider analytics.
Scorecard: View from the Feed - August 2026
Notional-weighted daily values, monthly median. Tile colour: blue = higher than the index's own trailing 6-month baseline, tangerine = lower, grey = no data, or in line with 6 months median

 Download chart
Fill Probability
The probability that an order placed at the 1st level of the book will be filled within 60 seconds.
8 indices, notional-weighted daily values, monthly median/IQR. Bar colour: blue = higher than the panel mean this month, tangerine = lower.

 Download chart
Quote to Trade
The number of quote messages per executed trade.
8 indices, notional-weighted daily values, monthly median/IQR. Bar colour: blue = higher than the panel mean this month, tangerine = lower.

 Download chart
Volatility
Intraday volatility computed over the trading session.
10 indices, notional-weighted daily values, monthly median/IQR. Bar colour: blue = higher than the panel mean this month, tangerine = lower.

 Download chart
TWA Spread
The time-weighted mean bid-ask spread of the day, given in basis points relative to the time-weighted mean mid-point price.
8 indices, notional-weighted daily values, monthly median/IQR. Bar colour: blue = higher than the panel mean this month, tangerine = lower.

 Download chart
Auction Dislocation
The change (in basis points) between the mid-point price 1 minute prior to the end of continuous trading and the closing price of the auction on the Regulated Market.
10 indices, notional-weighted daily values, monthly median/IQR. Bar colour: blue = higher than the panel mean this month, tangerine = lower.

 Download chart
Liquidity
The time-weighted average notional amount up to 30 basis points around the BBO.
10 indices, notional-weighted daily values, monthly median/IQR. Bar colour: blue = higher than the panel mean this month, tangerine = lower.

 Download chart
Mean Resting Time
The mean time, in seconds, that an order placed at the 1st level of the book will sit on the book before being filled.
7 indices, notional-weighted daily values, monthly median/IQR. Bar colour: blue = higher than the panel mean this month, tangerine = lower.

 Download chart
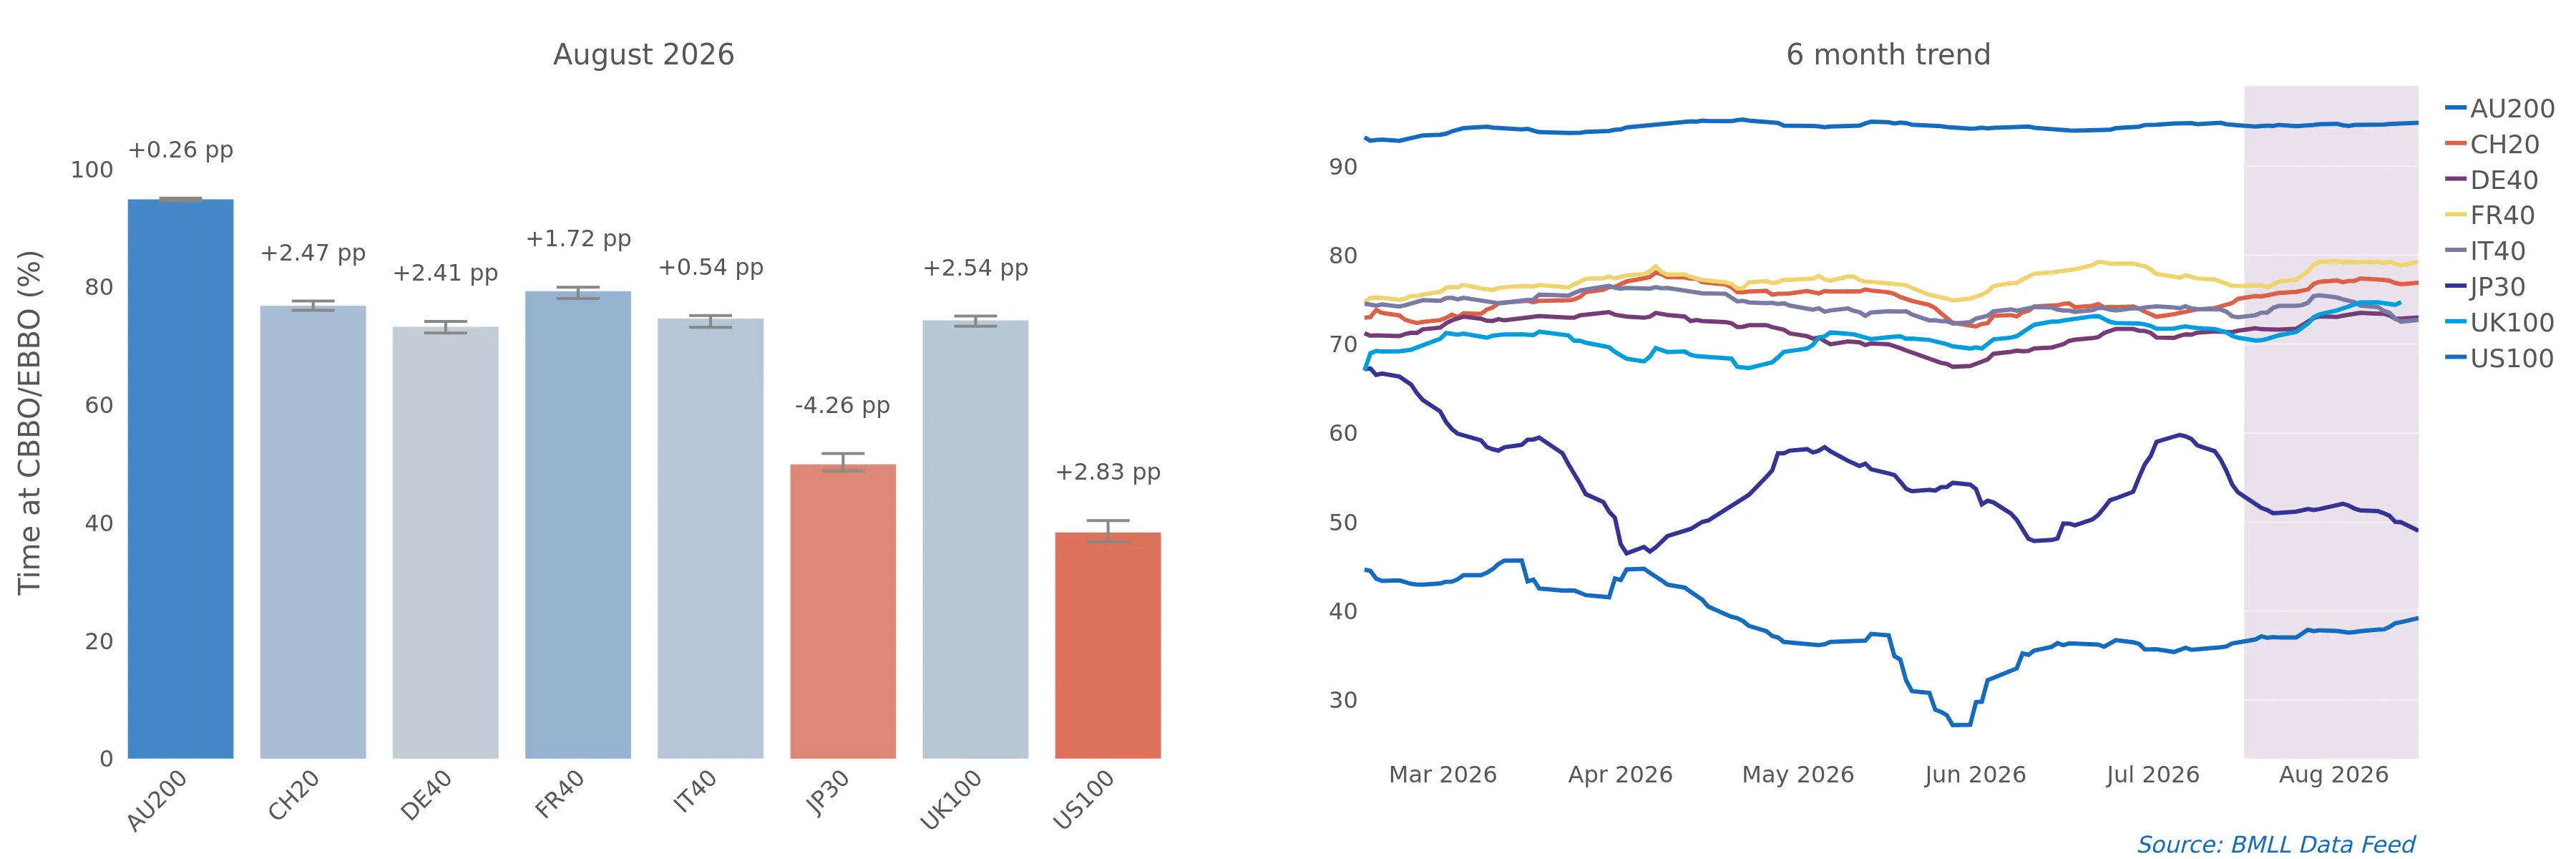
Time at CBBO/EBBO
The percentage of time during the continuous trading period where there is at least one order equal to the bid price and simultaneously at least one order equal to the ask price of the EBBO.
8 indices, notional-weighted daily values, monthly median/IQR. Bar colour: blue = higher than the panel mean this month, tangerine = lower.
 Download chart
1s Markout
The notional-weighted, signed 1-second markout in basis points, computed as (PostTradeMid1000ms - TradePrice) / TradePrice * 10000 with the sign flipped on aggressive sells.
10 indices, notional-weighted daily values, monthly median/IQR. Bar colour: blue = higher than the panel mean this month, tangerine = lower.

 Download chart
Indices:
- Europe - Cboe UK100, Cboe CH20, Cboe DE40, Cboe FR40, Cboe IT40
- APAC - AU200, JP30, CN50, HK82
- Americas - US100
Across an index, the values are aggregated using a weighted mean of the considered metric with the lit trade notional of that listing and smoothed using a 10-day rolling average. The Notional Liquidity and Trade Notional has been converted to Euros from all other currencies. The conversion rate uses the daily rate published by the ECB. On each bar chart, the white whiskers span the 25th to the 75th percentile, also weighted by the lit trade notional, to show the distribution width.
These metrics are built from BMLL's pre-calculated daily analytics, available via the BMLL Data Feed and can be delivered directly into your existing workflows.
Contact us to discuss how this can support your market microstructure research, TCA and liquidity provider analytics.
Explore other Market Insights:
BMLL Market Lens: European Liquidity Maps
BMLL Market Lens: US Liquidity Maps